You’ve worked hard. You’ve built a business, scaled your income, and watched your portfolio grow. But as you approach the finish line, a silent predator is waiting.
It’s called the Tax Time Bomb.
Most successful entrepreneurs are sitting on a mountain of "tax-deferred" assets. Think 401(k)s, IRAs, and SEP IRAs. You’ve been told for decades that these are the "smart" way to save. But there’s a catch: and it’s a big one.
When you go to withdraw that $2M portfolio in retirement, the IRS is going to show up as your uninvited business partner. If tax rates go up (and let's be honest, look at the national debt: where else are they going?), that $2M could quickly look more like $1.2M.
What if you could keep the whole $2M? What if you could engineer a 0% tax bracket retirement strategy that allows you to pull six-figure income without paying a single dime to the IRS?
It’s not just a dream. It’s a roadmap. Here are the 5 steps to get there.
Step 1: Audit the "Tax Time Bomb"
The first step in tax-free retirement planning is knowing exactly where you stand. Most business owners have a "reactive" strategy: they look at their taxes once a year in April and try to minimize that year's bill.
That is a mistake.
To reach a 0% bracket, you must stop thinking about this year’s taxes and start thinking about your lifetime tax bill.
- Audit your current assets: How much of your net worth is "forever taxed" (Brokerage accounts)? How much is "tax-deferred" (401k)? How much is truly tax-free?
- Evaluate your entity structure: Are you an LLC taxed as an S-Corp? Are you maximizing your business deductions to lower your current bracket while you're in your peak earning years?
You need to know the size of your "tax debt" to the government. If you have $2M in a traditional IRA, you don't actually have $2M. You have $2M minus whatever the tax rate is in 15 years. Are you willing to gamble your lifestyle on what Congress decides the tax rate should be?
Step 2: Master the Three-Bucket Strategy
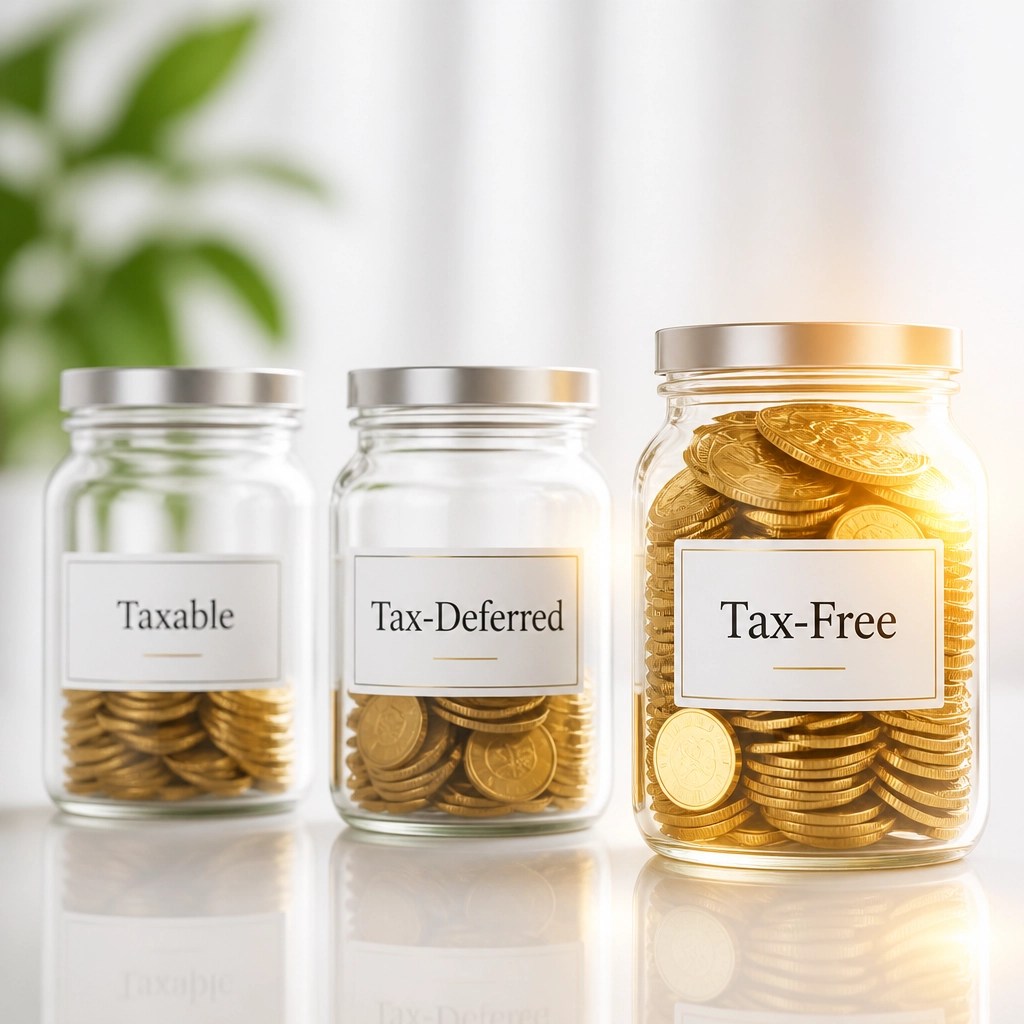
Professional retirement planning for small business owners relies on diversification: not just in what you buy, but how it's taxed. Think of your money in three distinct buckets:
- The Taxable Bucket: Your savings, CDs, and brokerage accounts. You pay taxes on the growth every year. It’s accessible, but inefficient.
- The Tax-Deferred Bucket: Your 401(k)s and IRAs. You got a break today, but you'll pay the piper tomorrow. Worst of all, these accounts trigger Required Minimum Distributions (RMDs), meaning the government forces you to take the money out (and pay taxes) whether you need it or not.
- The Tax-Free Bucket: Roth IRAs, HSAs, and the "secret weapon": Indexed Universal Life (IUL). This is where the magic happens.
To hit a 0% bracket, your goal is to systematically move money from Buckets 1 and 2 into Bucket 3. The more you have in the Tax-Free Bucket, the less control the IRS has over your life.
Step 3: Proactive Shifting & "Filling the Bracket"
You don't just wake up in a 0% bracket. You build it. This is where wealth protection for entrepreneurs becomes an art form.
One of the most powerful moves you can make is "Filling the Bracket." In years where your business income is lower, or in the "gap years" between retirement and starting Social Security, you can strategically convert portions of your tax-deferred IRA into a tax-free Roth or IUL.
- Realize capital gains at 0%: If your taxable income is low enough, you can actually harvest long-term capital gains at a 0% federal tax rate.
- Roth Conversions: Pay the tax now at a known, lower rate to ensure you never pay it again.
Think of it as "clearing the path." You are paying a small toll now to avoid a massive roadblock later. By the time you reach age 72, you want your taxable income to be so low that RMDs don't push you into a higher bracket.
Step 4: Shield Your Social Security
Did you know that up to 85% of your Social Security benefits can be taxed?
It’s called the "Tax Torpedo." If your "provisional income" (which includes half of your Social Security plus your other taxable income) crosses a certain threshold, the IRS starts taking a cut of your benefits.
For many retirees, this creates a devastating cycle: they take money out of their 401(k) to pay bills, which triggers taxes on their Social Security, which requires them to take more money out of their 401(k) to pay the extra tax.
Stop the madness.
When you have a robust 0% tax bracket retirement strategy, your income comes from the Tax-Free Bucket. Because Roth and IUL distributions don't count toward your "provisional income," you can keep your Social Security benefits 100% tax-free.
That is the difference between surviving retirement and thriving in it.
Step 5: The IUL Engine (Your Secret Weapon)

The final piece of the puzzle is the Indexed Universal Life (IUL) policy. This is often the most misunderstood tool in the financial shed, but for business owners, it is a powerhouse.
An IUL provides:
- Tax-free growth and tax-free distributions.
- Market protection: Your money is linked to an index (like the S&P 500), but you have a 0% floor. If the market crashes 30%, you lose 0%.
- No contribution limits: Unlike a 401(k) or Roth IRA, there is no IRS limit on how much you can put into a properly structured IUL.
In our previous post, IUL vs. 401(k): Which Strategy Actually Builds More Tax-Free Wealth?, we broke down why the IUL is often the superior choice for entrepreneurs who want flexibility and 0% tax exposure.
Think of the IUL as your "Private Reserve Bank." It gives you the liquidity to fund your business, the protection to safeguard your family, and the tax-free income to fuel your dream retirement.
Common Questions About the 0% Tax Strategy
"Is this legal? It sounds too good to be true."
Absolutely. These are not "loopholes." These are IRS-sanctioned tax codes. The difference is that most CPAs are trained to look backward at what you've already done. We look forward to what you're going to do.
"I already have a 401(k). Is it too late?"
It’s never too late, but the sooner you start shifting, the less "tax friction" you'll encounter. Even if you are 60 years old, a 5 or 10-year strategy can save you hundreds of thousands of dollars in lifetime taxes.
"What if tax laws change?"
Tax laws always change. That’s exactly why we use a "multi-bucket" approach. By diversifying your tax status, you are protected no matter which way the political wind blows.
Your Next Move
The "Tax Time Bomb" is ticking. Every day you wait is a day you leave your future wealth up to chance.
At Catherine, we specialize in helping individuals and business owners navigate these major transitions. We don't just sell products; we build strategies for a 0% tax bracket retirement.
Are you ready to take control? Let's build your tax-free legacy together.
👉 Schedule your 0% Tax Strategy Consultation here.
👉 Learn more about our services at cathyagada.com.
Don't let the IRS be your biggest beneficiary. Take the first step today.